


Immigration
8/10/2026
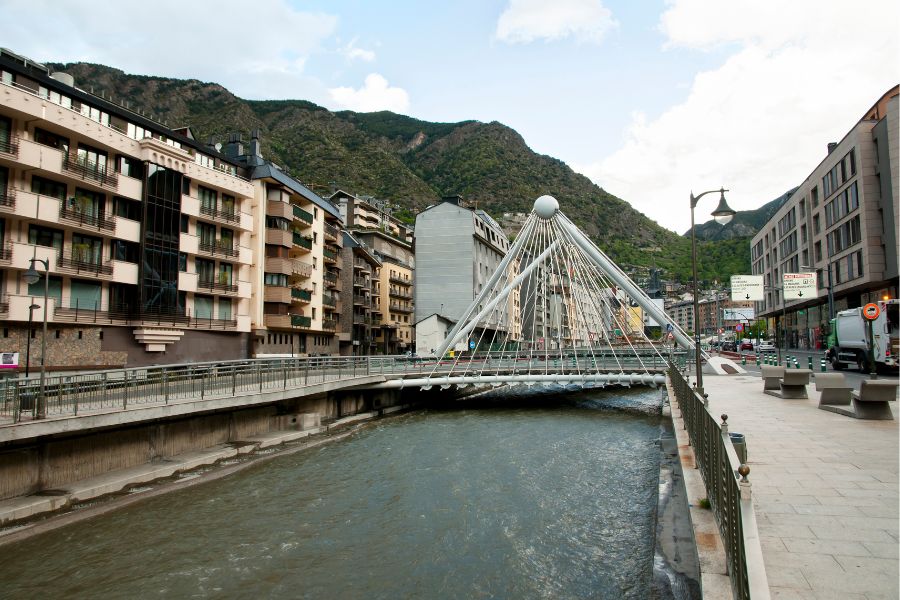
Located between France and Spain, Andorra attracts a growing number of investors and expatriates each year who wish to acquire property there. Many of them wonder whether it is possible to finance a purchase through a loan, and under what conditions. The answer is yes: Andorran banks grant mortgage loans to residents and non-residents alike. The market nonetheless remains more demanding than in France, with a higher down payment, a more robust application file, longer banking timeframes and, for foreign buyers, an acquisition framework that has been strictly regulated since 2025. This guide sets out the conditions, the rates, the lending banks and the steps to follow.
Andorra has a solid and regulated banking system, supervised by the Autoritat Financera Andorrana (AFA). Local institutions offer a range of financing solutions, both for individuals residing in the Principality and for foreign buyers.
Financing a property is therefore accessible provided a serious application is submitted. Andorran banks grant loans to residents and non-residents, but the conditions differ appreciably between these two profiles. A resident generally benefits from more flexible conditions thanks to their local roots, whereas a non-resident must provide additional guarantees.
For an Andorran resident, the bank primarily requires proof of stable income, an employment contract or a local professional activity, as well as a sound financial situation. A banking history free of incidents and regular income are most often sufficient to put together an admissible application.
For a non-resident, the review of the application is stricter. Banks exercise greater vigilance and avoid taking risks when the borrower resides abroad. They require a higher down payment, a solid mortgage guarantee and proof of income earned abroad.
High-risk profiles and those subject to banking prohibitions cannot qualify for a mortgage loan in Andorra. It is necessary to have fixed income and to present a solid banking history. The level of down payment required varies from one institution to another, but it is generally higher for a non-resident buyer than what is usually the practice in France.
In practice, most Andorran banks limit monthly repayments to around 35% of income, but this threshold is a matter of each institution's internal policy rather than a legal rule: each bank sets its own ratios. This debt-service ratio corresponds to the relationship between the repayment charges and the borrower's regular net income. A level of indebtedness above this threshold at the time of the application generally blocks access to credit.
A non-resident wishing to acquire property in Andorra must obtain a foreign real estate investment authorization, the autorització d'inversió estrangera immobiliària. Since 2025, this authorization has been capped: a foreign investor may, in principle, acquire over a ten-year period only a single dwelling plus a limited number of properties (up to two apartments and their annexes, or six parking spaces). Certain investments are excluded, notably those intended for tourist rental, and the authorization may be refused on grounds of public order or protection of the housing market.
Andorran banks offer three main types of mortgage loan. The fixed-rate loan guarantees constant monthly repayments throughout the term of the loan, regardless of market fluctuations: this is the option that offers the most stability and predictability. The variable-rate loan adjusts its monthly repayments according to a reference index, with the potential for savings if rates fall, but a risk of an increase if they do not. The mixed-rate loan combines an initial fixed-rate period followed by a variable-rate period.
The rates of Andorran variable-rate mortgage loans are indexed to the Euribor, the reference index for interbank rates in the euro area. The rate applied corresponds to the Euribor plus a margin, set by each institution according to the borrower's profile. As the Euribor changes continuously, the rate of a variable loan is revised according to the chosen periodicity, often each year for the 12-month Euribor.
The rates applied vary from one institution to another and change with the market: there is no common scale across Andorran banks. The rate obtained depends on the borrower's profile (residence, income, down payment), the loan term and the type of rate chosen, and is negotiated on a case-by-case basis. To compare offers, the most reliable approach remains to consult several institutions, some of which offer online simulators.
Three institutions account for the bulk of mortgage loan applications in the Principality: Andbank, MoraBanc and Creand. All are regulated by the AFA, which guarantees a safe and transparent environment. BancSabadell d'Andorra, a subsidiary of the Spanish group, rounds out the offering for buyers already in a relationship with this group.
Andbank is particularly well suited to international investors, with tailored solutions, and offers both fixed-rate and variable-rate loans. MoraBanc stands out for its flexibility and its online simulators, which make it possible to quickly estimate borrowing capacity. Creand, the former Crèdit Andorrà, offers packages that often include insurance and wealth management, with a financing ratio determined according to the borrower's profile and application.
Andorran banks also offer loans backed by a mortgage guarantee whose amount can be customised according to the borrower's needs and resources.
| Bank | Strengths | Relevant profiles |
|---|---|---|
| Andbank | Tailored solutions, fixed-rate or variable-rate loans | International investors |
| MoraBanc | Flexibility, online simulators to estimate borrowing capacity | Borrowers who want a quick initial estimate |
| Creand | Packages that often include insurance and wealth management | Real estate projects integrated into a wealth strategy |
| BancSabadell d'Andorra | Subsidiary of the Sabadell group | Clients already in a relationship with the group |
The amount financed, the repayment term and the rate are set by each institution according to the borrower's profile and application.
Putting together the application requires gathering several supporting documents. The documents generally requested are as follows:
Beyond these documents, the bank requires a guarantee to cover the risk of non-repayment. This guarantee most often takes the form of a mortgage on the financed property. Borrower's insurance, which covers the outstanding capital in the event of an unforeseen situation, is also frequently requested. The bank then assesses the application, analysing in particular the borrower's solvency and the value of the property before making a loan offer.
The financing process follows a precise logic, which it is best to anticipate in order to avoid unpleasant surprises. The main steps are as follows:
Non-residents must also take into account anti-money-laundering checks, which lengthen the timelines, and French reporting obligations. The opening of a bank account in Andorra must accordingly be declared to the French tax authorities, as must, where applicable, the income derived from the property and its value for IFI purposes.
Purchasing a property in Andorra often forms part of a broader wealth strategy. Andorran taxation, known for its moderation, is one of the main attractions for foreign investors. The foreign buyer must nonetheless factor in the tax on foreign real estate investment, the rate of which is 6% of the actual value of the property for a dwelling, and 10% beyond the authorised acquisition limits. The double taxation avoidance treaty signed between France and Andorra also provides a clear framework for the treatment of property income, which secures the project for French buyers.
The payment of the monthly instalments benefits from another practical advantage: as Andorra uses the euro, no currency exchange fees apply to repayments made from France, and the security protocols put in place by the banks guarantee reliable transactions, whether the borrower is in the Principality or abroad.
Financing a property purchase in Andorra from France involves several particularities that must be factored in from the outset. The personal contribution required is higher than in France, the anti-money-laundering documentation is more extensive and the banking timelines are longer.
The transposition into Andorra of European anti-money-laundering standards has changed the financing process, with more thorough checks on the origin of the funds. Borrowers whose income is irregular, alternating between years with and without income, also encounter greater difficulty in obtaining approval. Thorough preparation of the file and the support of a local professional remain the best assets for seeing the project through to completion.
Obtaining a real estate loan in Andorra is an accessible process for those who prepare their file carefully and are familiar with local banking conditions. Between the choice of bank, the constitution of guarantees, the investment authorisation for non-residents, now capped, and the reporting obligations, each stage deserves to be anticipated. Specialist support makes it possible to save time, secure the procedures and negotiate conditions suited to your situation.
Would you like to establish yourself and invest in the Principality? Book your free 30-minute call to review your situation!
